PM Mudra Loan Guide: ₹50,000 से ₹20 लाख Categories, Tarun Plus की शर्त और Bank Appraisal NEW
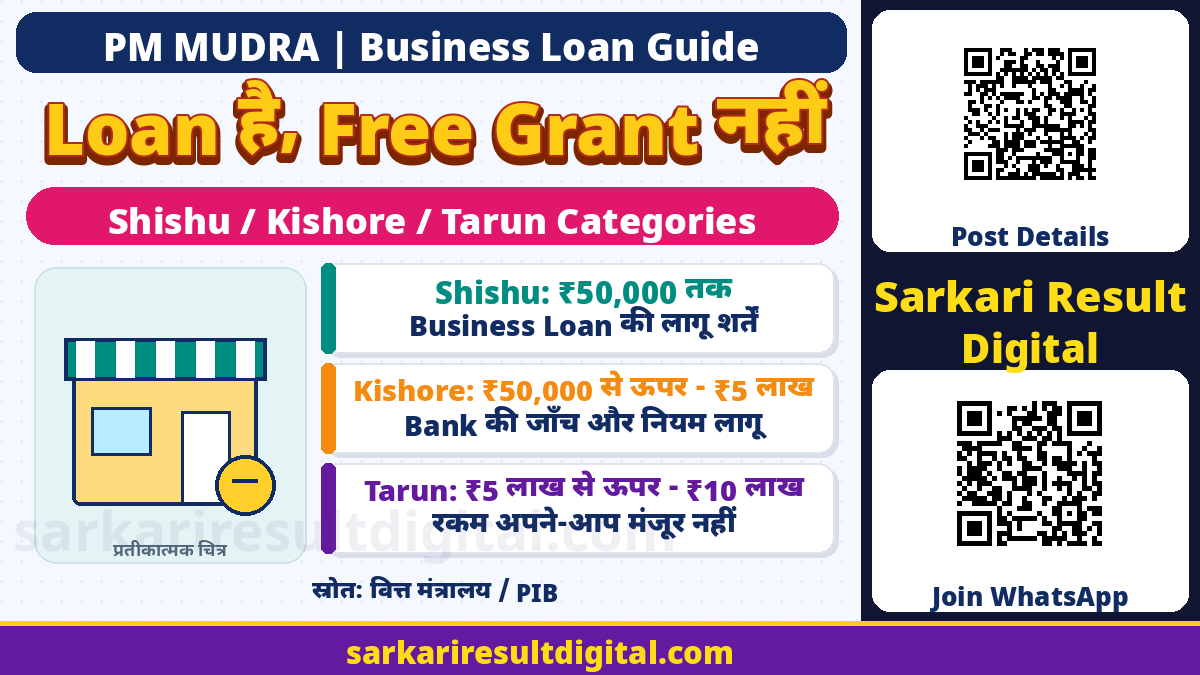
PM Mudra Loan Guide: प्रधानमंत्री मुद्रा योजना यानी PMMY छोटे और micro businesses के लिए institutional credit की व्यवस्था है। यह free cash grant या हर applicant को मिलने वाला ₹20 लाख का भुगतान नहीं है। Loan की जरूरत business plan, income-generating activity और lender की जांच से जुड़ी है। मंजूर रकम तथा repayment conditions lender के sanction documents में पढ़नी होती हैं।
Ministry of Finance के official विवरण में चार loan categories हैं। ₹20 लाख तक की upper limit को Shishu या नए borrower की automatic entitlement न समझें। Tarun Plus के लिए पहले Tarun category का loan लिया और successfully repay किया होना जरूरी है। यह लेख scheme की सामान्य जानकारी है, किसी bank में आपके नाम से loan application या approval नहीं।
चार Categories की सही रकम
| विषय | क्या समझें |
|---|---|
| Shishu | ₹50,000 तक |
| Kishore | ₹50,000 से अधिक और ₹5 लाख तक |
| Tarun | ₹5 लाख से अधिक और ₹10 लाख तक |
| Tarun Plus | ₹10 लाख से अधिक और ₹20 लाख तक, previous Tarun loan की successful repayment की शर्त |
| Loan देने वाले | Eligible Member Lending Institutions, केवल किसी निजी WhatsApp agent का आश्वासन नहीं |
| क्या नहीं है | सभी के लिए guaranteed amount, interest-free पैसा या free subsidy का universal promise |
रकम की boundaries ध्यान से पढ़ें। ₹50,000 Shishu की upper boundary है; Kishore उससे ऊपर शुरू होता है। इसी तरह ₹5 लाख तक Kishore और ₹10 लाख तक Tarun का उल्लेख है। Tarun Plus “above ₹10 lakh and up to ₹20 lakh” है। केवल business का नाम लिखकर highest category चुन लेना पर्याप्त नहीं; genuine funding requirement और scheme conditions दोनों मिलनी चाहिए।
Tarun Plus में पिछला Loan क्यों जरूरी है?
25 October 2024 की Ministry of Finance release ने नई Tarun Plus category समझाते हुए स्पष्ट कहा कि entrepreneurs ने पहले Tarun loan लिया और उसे successfully repay किया हो। इसलिए “पहली बार business शुरू करो और सीधे ₹20 लाख पाओ” जैसा विज्ञापन अधूरा है। Previous loan की category और repayment record lender से verify कराएं।
किसी दूसरे personal loan, credit card या छोटी Shishu borrowing को केवल paid होने की वजह से Tarun eligibility का substitute न मानें। Official condition previous Tarun loan की है। Bank statement, loan account closure या repayment proof की कौन-सी documents जरूरत होगी, lender बताएगा। इस guide ने कोई fixed look-back period, automatic enhancement या sanction deadline नहीं बनाई है।

किन Business Activities के लिए है?
Official Ministry reply manufacturing, trading और services के income-generating activities के साथ agriculture-allied activities का उल्लेख करती है। Poultry, dairy और beekeeping जैसे उदाहरण PIB के official scheme summary में आते हैं। इसका अर्थ हर crop loan, household expense या personal purchase को PMMY मान लेना नहीं। Proposed activity और खर्च का उद्देश्य lender को साफ बताएं।
व्यवसाय नया हो या existing activity का विस्तार, वास्तविक eligibility और suitable category lender से समझें। Working capital और asset purchase जैसी जरूरतों में item-wise estimate उपयोगी है, लेकिन यहां किसी bank की exact product structure को सभी lenders पर लागू नहीं किया गया। Household consumption का खर्च business project में छिपाना या fake quotation देना सही आवेदन नहीं है।
Loan कौन देता है?
PMMY में institutional lending Member Lending Institutions के जरिए होती है। Ministry के विवरण में Scheduled Commercial Banks, Regional Rural Banks, NBFCs और Micro Finance Institutions शामिल हैं। Government scheme का नाम देखकर किसी निजी website, agent या social-media account को loan sanctioning authority न मानें। अपनी चुनी हुई institution की official branch या verified digital channel से ही route लें।
Application लेने वाला platform और final lender अलग हों तो दोनों की भूमिका पढ़ें। एक reference number मिलना bank sanction नहीं है। Business plan और otherwise eligible borrower की condition बनी रहती है। किसी portal पर “eligible” result या document upload पूरा होने से loan disbursal का unconditional promise नहीं बनता। Bank की actual communication और written terms निर्णायक हैं।

Collateral-free का मतलब क्या नहीं है?
Ministry of Finance PMMY को collateral-free institutional credit बताती है। फिर भी credit appraisal, identity checks, business viability और repayment capacity की जरूरत समाप्त नहीं होती। Collateral-free को “बिना documents”, “बिना जांच” या “पैसा वापस नहीं करना” न पढ़ें। Applicant की दी हुई facts और lender के acceptable record के आधार पर decision होता है।
Official October 2024 release ₹20 लाख तक PMMY loans के लिए CGFMU guarantee coverage बताती है। यह guarantee framework borrower के लिए free money या repayment waiver नहीं है। Specific security, guarantee documentation या sanction condition समझ न आए तो lender से लिखित clarification लें। किसी agent का “सरकार भर देगी, EMI मत देना” कहना official repayment obligation का विकल्प नहीं।
Documents की तैयारी कैसे करें?
इन official Ministry summaries में सभी banks के लिए एक identical universal upload checklist नहीं दी गई है। इसलिए यहां PAN, GST, income proof या specific certificate को हर applicant पर बिना exception mandatory नहीं बताया गया। Lender की current checklist और business type के अनुसार applicable KYC, address, enterprise और financial records तैयार करें।
- Business क्या है, कितनी funding चाहिए और उसका उपयोग क्या होगा, यह लिखें।
- Actual estimates, existing business records और उपलब्ध financial details व्यवस्थित करें।
- Identity, address और business name की spelling सभी records में मिलाएं।
- Tarun Plus के लिए previous Tarun borrowing और successful repayment का lender-verifiable record रखें।
- हर document की readable copy दें; blank declaration या गलत financial statement sign न करें।
- Official receipt/application reference और submitted version की सुरक्षित copy रखें।
यदि lender additional information मांगे तो उसकी exact requirement और official submission route पढ़ें। किसी stranger को OTP, bank password या remote-access permission देकर application “unlock” न कराएं। Processing fee, inspection charge या insurance payment बताया जाए तो lender की written schedule से verify करें, निजी UPI collection को scheme का compulsory government fee न मानें।
Interest, Repayment और Charges
यह लेख सभी PMMY loans के लिए एक fixed interest rate, fixed EMI, common tenure या zero processing fee का दावा नहीं करता। Actual quoted rate, calculation method, repayment schedule और applicable charges lender से लें। Loan agreement तथा sanction letter पढ़ें और total repayment burden अपनी business cash flow से मिलाएं। Scheme category maximum है, सस्ती या free credit की universal guarantee नहीं।
Subsidy, credit guarantee और interest concession अलग बातें हैं। किसी अन्य scheme से मिलने वाला benefit अपने आप PMMY loan में शामिल न मानें। Moratorium या repayment holiday offer हो तो interest treatment, first instalment date और total cost लिखित रूप में समझें। Affordability और final terms जाने बिना केवल highest available amount लेने का निर्णय न करें।
Application से Disbursal तक अलग Stages
पहले official lender route और applicable PMMY product चुनें, फिर complete और सही application दें। Verification, clarification, appraisal, sanction, agreement और disbursal अलग stages हो सकते हैं। Status pending हो तो reference के साथ lender से पूछें; हर बार नया form भरकर approval तेज होने का अनुमान न लगाएं।
Sanction मिलने पर borrower name, business purpose, amount, interest, charges और repayment dates जांचें। Sanction amount और खाते में actual credited amount में अंतर हो तो disbursal statement से समझें। किसी complaint या correction के लिए पहले lender का official customer-support/grievance route इस्तेमाल करें। यह guide किसी individual loan को approve या recover नहीं करती।
अक्सर पूछे जाने वाले प्रश्न
क्या हर नया Applicant ₹20 लाख पा सकता है?
नहीं। Tarun Plus के लिए previous Tarun loan लिया और successfully repay किया होना जरूरी है; final appraisal lender करता है।
क्या Mudra एक Free Grant है?
नहीं। यह institutional business loan है; sanction और repayment terms लागू हैं।
क्या केवल Banks ही Loan देते हैं?
Official list में SCBs, RRBs, NBFCs और MFIs जैसे Member Lending Institutions हैं।
क्या Collateral-free का मतलब No Checking है?
नहीं। Identity, business plan, eligibility और repayment appraisal अलग हैं।
क्या सभी के लिए एक Interest Rate है?
इन official summaries से कोई universal fixed rate साबित नहीं होता; lender की current terms पढ़ें।
क्या Registration ही Approval है?
नहीं। Application/reference, sanction और actual disbursal अलग stages हैं।
Official links और मूल स्रोत
- Ministry of Finance, 25 October 2024: Tarun Plus और पिछला Tarun repayment
- Ministry of Finance, 25 March 2025: PMMY categories, lending institutions और business activities
- PIB August 2025: Financial inclusion और PMMY का official विवरण
Official स्रोत जांच: 16 नवंबर 2026। आगे के संशोधन और संबंधित authority के current निर्देश लागू होंगे।
प्रस्तुति और संकलन: Ashok Nayak | Sarkari Result Digital