Deceased Bank Deposit Claim Guide: 15 Calendar Days, Nominee Documents और Delay Interest के नियम NEW
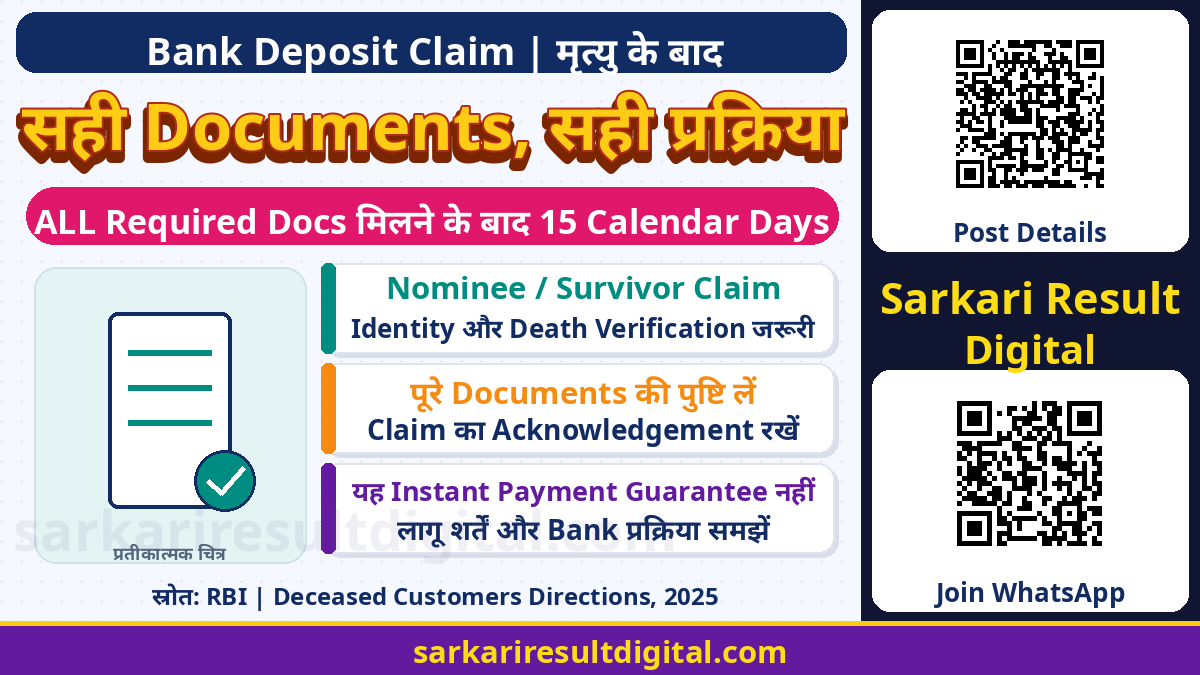
Deceased Bank Deposit Claim Guide: Bank depositor की मृत्यु के बाद परिवार को account की रकम लेने के लिए सही claim process समझना पड़ता है। Registered nominee, joint-account survivor और बिना nomination वाले legal heir का route एक जैसा नहीं होता। RBI की 26 सितंबर 2025 की Directions deposit claim को सभी जरूरी documents मिलने के बाद अधिकतम 15 calendar days में settle करने की व्यवस्था बताती हैं। यह केवल पहली enquiry के बाद तुरंत payment की गारंटी नहीं है।
यह guide मुख्य रूप से bank deposit के nominee/survivor claim, documents, acknowledgement और delay की शर्तों पर है। यह किसी परिवार का succession decision, bank payment approval या रकम transfer करने की सेवा नहीं। Nomination register करने, locker का rent/security और deceased deposit settlement को अलग processes मानें। अपने account का actual mandate और current applicable instructions जांचें।
कौन-से Banks और Products इस Framework में हैं?
RBI की Settlement of Claims in respect of Deceased Customers of Banks Directions, 2025 commercial banks और co-operative banks पर लागू हैं। Source में implementation जल्द-से-जल्द और अधिकतम 31 मार्च 2026 तक करने का निर्देश है। Depositor की definition में savings, current और term deposit जैसे bank deposit accounts आते हैं। Account की nature पहले पहचानें।
इसी Directions में bank-administered government savings schemes, जैसे Public Provident Fund और Senior Citizen Savings Scheme, को अलग रखा गया है। उनकी claim settlement संबंधित scheme provisions के अनुसार होगी। इसलिए bank branch में PPF होने से इस article का हर deposit rule उसी तरह लागू न मानें। Insurance, EPF, pension और mutual fund के claims भी इस guide से स्वतः तय नहीं होते।
| विषय | क्या देखें? |
|---|---|
| Coverage | Commercial और co-operative banks के applicable deposit claims |
| Deposit examples | Savings, current और term deposit |
| PPF/SCSS | अलग scheme provisions लागू |
| Article focus | Deposit settlement, locker release नहीं |
Nominee और Survivor की भूमिका अलग समझें
Registered nominee और survivorship clause वाले joint-account survivor के claim की conditions Directions में दी गई हैं। Bank को nominee/survivor की identity और account holder की death के documentary evidence पर due care करनी होती है। Payment रोकने वाला competent court order bank की जानकारी में न हो, यह भी जरूरी condition है। केवल family relation बताने से registered nomination सिद्ध नहीं होता।
Bank लिखित रूप से स्पष्ट करता है कि nominee/survivor legal heirs के trustee के रूप में payment प्राप्त करता है। इससे अन्य व्यक्ति के lawful right या claim समाप्त नहीं हो जाते। इसलिए nominee को बिना qualification पूरे estate का final owner घोषित न करें। Disputed inheritance पर यह article व्यक्तिगत कानूनी निष्कर्ष नहीं देता; actual facts और competent legal process महत्वपूर्ण हैं।

Joint Account में Nominee कब Claim करता है?
Directions कहती हैं कि joint deposit account में, survivorship clause हो या न हो, nominee का right सभी depositors की मृत्यु के बाद arises होता है। एक joint holder की मृत्यु पर surviving holder, registered mandate और applicable process को अलग देखना होगा। Joint account को केवल deceased व्यक्ति का sole account मानकर form न भरें।
Account title, holders, either-or-survivor जैसी instructions और nomination record bank से मिलाएं। किसी पुराने form या family की याद से final mandate तय न करें। Survivor payment, nominee payment और legal-heir distribution एक ही बात नहीं। कोई injunction या dispute हो तो उसे छिपाकर simplified payment मांगना सही process नहीं है। Bank को actual स्थिति की जानकारी दें।
| विषय | क्या देखें? |
|---|---|
| Sole account | Registered nominee और applicable claim conditions |
| Joint account | सभी holders और survivor mandate देखें |
| Nominee right | Joint deposit में सभी depositors की मृत्यु के बाद |
| Ownership dispute | Nomination अकेले final inheritance judgment नहीं |
Nominee/Survivor के मुख्य Documents
Paragraph 9 के nominee/survivor case में duly signed claim form, deceased depositor का death certificate और claimant का identity तथा address verify करने वाला Officially Valid Document मांगा गया है। Claim form का source Annex I-A है। Current bank form में सही account और claimant details भरें। किसी और account के specimen में saved personal details copy न करें।
OVD का अर्थ केवल कोई भी photo या public social profile नहीं है; applicable KYC definition वाला accepted document समझें। Bank से current accepted document और physical/equivalent e-document requirements स्पष्ट करें। Claim की circumstances बदलें, nomination discrepancy हो या कोई अलग legal route लागू हो, तो generic three-document checklist को हर case की exhaustive list न मानें।
क्या Succession Certificate हर Nominee को देना होगा?
RBI Directions paragraph 9 के अनुसार stated conditions पूरी होने वाले nominee/survivor payment में bank को Succession Certificate, Letter of Administration या Probate of Will जैसे legal documents पर insist नहीं करना चाहिए। उसी covered case में nominee/survivor/third party से indemnity या surety भी नहीं मांगनी है, account balance की amount चाहे जो हो।
इस rule को बिना nomination वाले legal-heir case, contesting claims या restraining court order के लिए universal exemption न बनाएं। पहले यह पता करें कि आपका claim वास्तव में किस paragraph और registered record में आता है। Bank अतिरिक्त document मांगे तो exact reason और लागू claim category लिखित में पूछें, बिना facts समझे सारे legal papers अनावश्यक घोषित न करें।
| विषय | क्या देखें? |
|---|---|
| Covered nominee case | Paragraph 8-9 की सभी conditions के साथ |
| Legal certificates | Covered case में universal insistence नहीं |
| Indemnity/surety | Covered nominee/survivor case में नहीं |
| Different case | No nominee/dispute/Will में अलग procedure |

Claim किसी भी Branch में देने का नियम
Paragraph 29 claimant को bank की किसी भी branch में acknowledgement के साथ claim lodge करने की अनुमति देता है। इसका मतलब किसी भी अलग bank में claim देना नहीं है। उसी bank का सही account/deposit reference दें और branch से receipt लें। Bank के standardized claim forms और case-wise document procedure branches तथा website पर उपलब्ध होने चाहिए।
पहली receipt और सभी required documents प्राप्त होने की confirmation अलग records हो सकते हैं। Form जमा करने की date, किस branch ने लिया, reference number और accompanying documents की list सुरक्षित रखें। किसी staff को केवल informal message भेजना या blank form का photo रख लेना formal claim acknowledgement का पर्याप्त substitute नहीं है।
Incomplete Documents पर क्या मिलना चाहिए?
Directions bank को claim acknowledge करते समय pending, incomplete या incorrect documents की list बताने को कहती हैं। बाद में सभी required documents मिलने पर bank को उसकी confirmation issue करनी है। यह record 15-calendar-day rule समझने के लिए महत्वपूर्ण है। केवल family की पहली visit की date से बिना document status देखे delay count न करें।
Bank कोई deficiency बताए तो उसका exact description पढ़ें। जो document दिया है उसकी copy और submission acknowledgement से compare करें। अस्पष्ट oral instruction के बजाय written list और receipt मांगना उपयोगी है। यह general record advice है, document authenticity या किसी actual claim की completeness का इस website द्वारा certification नहीं। गलत या fabricated death/identity record का उपयोग न करें।
| विषय | क्या देखें? |
|---|---|
| Claim receipt | Request मिलने का acknowledgement |
| Deficiency list | Pending/incomplete/incorrect documents का उल्लेख |
| Complete-document confirmation | सभी required documents मिलने की अलग पुष्टि |
| Timeline anchor | उसी complete-document receipt से applicable period |
15 Calendar Days कब से गिनें?
Paragraph 31 deceased customer के deposit-account claim को सभी required documents associated with the claim मिलने की date से अधिकतम 15 calendar days में settle करने का निर्देश देता है। Calendar days को 15 working days न लिखें। दूसरी तरफ केवल initial enquiry, death की date या incomplete application की date को automatic start point भी न मानें।
Source का rule और actual case का timeline record साथ देखें। Account details, complete-document confirmation, bank response और किसी court restriction की स्थिति महत्वपूर्ण होगी। यह article कोई arbitrary extra waiting period नहीं जोड़ता, लेकिन individual payment date या eligibility को पहले से approved भी नहीं बताता। Pending case में bank से factual status और reasons मांगें।

Bank-attributable Delay पर Interest
Paragraph 33 के अनुसार deposit claim निर्धारित period में settle न हो तो bank claimant को delay के reasons बताए। Delay bank के कारण हो तो settlement amount due पर delay period के लिए prevailing Bank Rate से कम-से-कम 4 percentage points अधिक annual interest के रूप में compensation दिया जाना है। इसे flat ₹100 या ₹5,000 per day वाला deposit rule न बनाएं।
Reference date के लिए Directions सभी required documents मिलने की date को रखती हैं। यहां prevailing Bank Rate का कोई current numerical quote या personal claim का calculation नहीं दिया गया है। Amount due, complete documents की date, actual settlement और delay attribution की जांच जरूरी है। Applicable records के साथ bank से written calculation मांगें; article को guaranteed payout order न समझें।
| विषय | क्या देखें? |
|---|---|
| Trigger | Prescribed period के बाद bank-attributable delay |
| Form | Settlement amount due पर interest |
| Rate | कम-से-कम prevailing Bank Rate + 4% per annum |
| यह नहीं | हर pending claim पर flat daily cash guarantee |
No Nominee, Will, FD और Locker की अलग बातें
Nomination न हो तो Directions में अलग simplified procedure और उसकी amount/condition-based documentation है। Will, contesting heirs या court order होने पर और अलग provisions हैं। केवल nominee वाले three documents देकर हर no-nominee claim settle होने की अपेक्षा न रखें। Bank से correct category, current standardized form और documents की पूरी written list लें।
Term deposit को death पर prematurely terminate करने और jointly held FD में consent/mandate की अलग conditions भी source में हैं। Locker या safe-custody claim के लिए 15-day provision inventory की date fix करने की communication से जुड़ा है, deposit-payment paragraph जैसा नहीं। इसलिए इस guide का deposit interest formula हर locker delay या PPF claim पर copy न करें। Privacy रखें और OTP/PIN/password देकर claim fast-track कराने का प्रस्ताव स्वीकार न करें।
अक्सर पूछे जाने वाले प्रश्न
15 दिन Working Days हैं या Calendar Days?
Deposit claim के लिए paragraph 31 में 15 calendar days हैं, सभी required documents मिलने की date से।
Nominee को हर बार Succession Certificate चाहिए?
Paragraph 8-9 की covered conditions वाले nominee/survivor case में ऐसे legal documents और indemnity/surety पर insist नहीं करना है। अलग claim category की conditions अलग हैं।
क्या Nominee ही Final Legal Owner बन जाता है?
Directions payment को legal heirs के trustee के रूप में बताती हैं; अन्य lawful rights/claims समाप्त नहीं होते।
Joint Holder की मृत्यु पर Nominee तुरंत आता है?
Joint deposit में nominee का right सभी depositors की मृत्यु के बाद arises होता है। Survivor mandate अलग देखें।
क्या हर Delay पर Fixed Daily Compensation है?
Deposit में bank-attributable delay पर settlement amount due के लिए कम-से-कम Bank Rate +4% per annum interest का rule है, flat daily rupee guarantee नहीं।
क्या PPF/SCSS को यही Rule लागू है?
Directions bank-administered government savings schemes को अलग scheme provisions के अनुसार रखती हैं। यह deposit-focused guide उन claims का substitute नहीं।
Official Links और मूल स्रोत
- RBI: Final Deceased-Customer Claim Directions, 26 September 2025, paragraphs 6-14 और 27-34
- RBI: Current Financial-Sector Notifications Directory
Official स्रोत जांच: 17 नवंबर 2026। आगे के संशोधन और संबंधित authority के current निर्देश लागू होंगे।
प्रस्तुति और संकलन: Ashok Nayak | Sarkari Result Digital