RTGS Transfer Guide: ₹2 लाख Minimum, 30 मिनट Credit, Return, Name Lookup और 22 Character UTR NEW
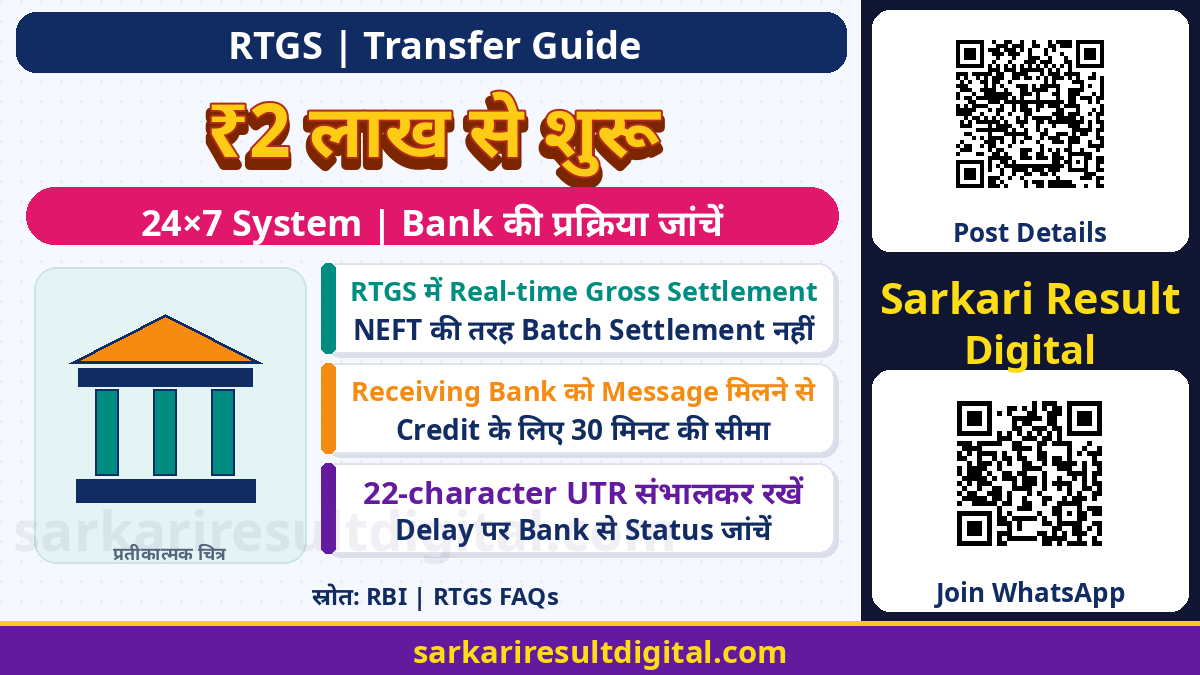
RTGS Transfer: बड़े value के bank transfer के लिए Real Time Gross Settlement system continuous, transaction-by-transaction settlement करता है। RBI system में minimum ₹2,00,000 है और upper ceiling नहीं है। फिर भी अपने bank account/channel की actual transaction limit, beneficiary details और current tariff अलग जांचना जरूरी है।
यह 18 नवंबर 2026 को पढ़े RBI के 14 अक्टूबर 2026 updated FAQ और May 2026 Version 1.1 System Regulations के customer-transaction sections पर आधारित guide है। Debit alert, beneficiary credit, positive confirmation और valid return अलग stages हैं। यहां कोई payment, beneficiary lookup या private banking login नहीं किया गया है।
RTGS और NEFT का फर्क पहले समझें
RTGS में settlement individual instructions के आधार पर real time होता है; NEFT में transactions batches में process होते हैं। केवल दोनों online bank transfer होने से उनका credit/return clock एक नहीं हो जाता। अपनी receipt या statement पर actual payment mode देखें। Bank ने customer का चुना mode दूसरे से बदल दिया है, ऐसा केवल timing देखकर अनुमान न लगाएं।
Current regulations 11.4 customers को RTGS/NEFT choice देने और chosen system में transfer की बात करती हैं। NEFT batch-settlement guide का B+2 clock RTGS पर copy न करें। इसी तरह UPI/ATM के fixed ₹100/day वाले कुछ failed-transaction rules हर RTGS case में लागू होने का दावा सही नहीं।
| विषय | क्या देखें? |
|---|---|
| RTGS | Continuous individual gross settlement |
| NEFT | Batch-based processing |
| Receipt | Actual payment mode पहले देखें |
| गलत तुलना | हर transfer में समान credit/refund clock |
24×7 System और ₹2 लाख Minimum
RBI FAQ RTGS को 24×7×365 available बताती है। Minimum amount ₹2 लाख है, RBI की ओर से system maximum ceiling नहीं। इसका मतलब bank internet/mobile channel पर हर amount बिना additional check के accept करेगा या physical branch counter रात में खुला होगा, ऐसा नहीं। Account restrictions और channel controls अलग हो सकते हैं।
FAQ कहती है RTGS future value-dated transactions accept नहीं करता और यह credit-push system है, जिसमें payer transfer शुरू करता है। किसी app की scheduled instruction feature और actual RTGS settlement को एक न मानें। पैसे पाने के लिए किसी अनजान व्यक्ति को अपने account से नया RTGS भेजने या credentials बताने की जरूरत नहीं माननी चाहिए।

Name Lookup में क्या दिखना चाहिए?
Account number और IFSC भरने के बाद beneficiary account name verify करने की free facility current regulations 11.20 में है। यह internet banking, mobile banking और branch पर उपलब्ध कराने का निर्देश है। Beneficiary registration, one-time transfer और पहले से registered beneficiary को दोबारा verify करने की सुविधा का संदर्भ दिया गया है।
नाम destination bank के Core Banking Solution से आता है। Name display न हो तो applicable alert के साथ remitter अपने discretion पर आगे बढ़ सकता है; इसलिए blank result को matched name न समझें। Regulation lookup reference number और bank logs का भी उल्लेख करती है। Dispute में ये records उपयोगी हैं, लेकिन यहां किसी third-party checker में bank details डालने की सलाह नहीं है।
Account Number की हर Digit जांचें
RTGS credit account number के आधार पर होता है। Beneficiary name message में जरूरी है, पर केवल spelling match को सही account का पर्याप्त प्रमाण न मानें। Verified bank details से number, account type और IFSC मिलाएं। बड़ी राशि भेजने से पहले बदली हुई bank details को किसी भरोसेमंद, पहले से ज्ञात माध्यम से confirm करना समझदारी है।
Regulation 11.3 गलत account में credit के मामलों के लिए bank grievance mechanism की बात करती है। इससे हर गलत transfer का instant cancellation या guaranteed recovery नहीं निकलती। RTGS settlement final और irrevocable होने के कारण error पता चलते ही remitting bank को लिखित जानकारी दें; केवल app में Cancel button खोजते हुए समय न गंवाएं।
30 मिनट की घड़ी कब शुरू होती है?
Beneficiary bank को अपने Member Interface पर payment message मिलने के बाद account तुरंत credit करना है और किसी दशा में 30 मिनट से आगे नहीं। यह ग्राहक के Send दबाने के समय से बिना किसी शर्त का end-to-end promise नहीं है। Originating bank के message release और beneficiary bank के credit stages अलग हैं।
Regulation 11.2 originating member को customer debit के 30 मिनट के भीतर payment message RTGS central system को release करने को कहती है। इसलिए debit time, UTR, receiving-message time और actual credit time अलग-अलग लिखकर जांचें। Receipt में सभी backend timestamps न हों तो bank से transaction trace और positive confirmation मांगें।
| विषय | क्या देखें? |
|---|---|
| Customer debit | Sender account से debit का समय |
| Message release | Originating member का अलग stage |
| Receiving Member Interface | Beneficiary credit clock का आधार |
| Credit deadline | Message receipt से अधिकतम 30 मिनट |

Credit न हो पाए तो Return का नियम
Account अस्तित्व में न होने या frozen होने जैसे कारणों से credit संभव न हो, तो regulation 11.8 receiving member को payment मिलने के एक घंटे के भीतर originating member को funds return करने को कहती है, RTGS availability के अधीन। Original transaction का UTR/transaction identification number return में भी रखा जाना है।
FAQ 18 एक घंटे की गणना Member Interface receipt से करती है और RTGS business day end, whichever earlier का उल्लेख भी रखती है। इसे customer के Send time से guaranteed one-hour account refund न लिखें। Remitting bank को return मिलने के बाद original customer debit reverse करना होता है। Bank से पूछें कि मामला pending credit है, valid return है या debit reversal अभी बाकी है।
Credit Delay और Return Delay का Compensation अलग
May 2026 regulation 11.7 delayed beneficiary credit पर current repo rate plus 2% के आधार पर प्रत्येक दिन compensation बताती है। Same-day credit delay में भी एक दिन का compensation है और eligible customer को बिना request automatic credit करना है। यह beneficiary customer से जुड़ा नियम है, fixed ₹100/day rule नहीं।
Regulation 11.9 delayed return में recipient member की compensation liability originating member तक और अंततः originating customer के account तक बताती है। FAQ 20 के credit-delay heading के नीचे return वाली wording दोहराई गई है, इसलिए यहां credit-delay के लिए स्पष्ट regulation 11.7 पर भरोसा किया गया है। कोई current numerical repo rate या अपनी बनाई interest calculation नहीं दी जा रही; bank से applicable rate, delay period और calculation record लें।
| विषय | क्या देखें? |
|---|---|
| Delayed credit | 11.7: beneficiary customer; repo rate plus 2% |
| Same-day delay | 11.7: एक दिन का compensation |
| Delayed return | 11.9: आखिर में originating customer |
| Automatic credit | Eligible case में request की शर्त नहीं |
Bank Charges: हर RTGS Free नहीं
RBI FAQ inward RTGS को free बताती है। Outward ₹2 लाख से ₹5 लाख तक charge ceiling ₹25 और ₹5 लाख से ऊपर ₹50 है, applicable tax अलग है। Banks lower charges ले सकते हैं। इसलिए किसी एक bank की free internet banking सुविधा को पूरे RTGS system का zero-charge promise न बनाएं।
Transfer confirm करने से पहले अपने bank का current channel-wise tariff देखें। Principal, displayed charge और tax अलग समझें। Free name lookup की बात और actual outward transfer charge दो अलग विषय हैं। यहां bank-specific tariff की जांच या किसी account का fee quote नहीं दिया गया है।

22 Character UTR और Positive Confirmation
RTGS UTR एक 22 character unique transaction reference है। Receipt और statement में इसे सुरक्षित रखें। RBI FAQ customer के लिए public self-service transaction tracker उपलब्ध होने का दावा नहीं करती; positive confirmation receiving bank से remitting bank और फिर customer तक जाती है। UTR किसी अनजान refund website में डालना status check का जरूरी रास्ता नहीं।
Bank को complaint में amount, transfer mode, transaction date/time, UTR, debit entry और beneficiary-credit evidence दें। Full account credentials, PIN या OTP किसी को न भेजें। Ask करें: credit हुआ या return? receiving time क्या है? return reason क्या है? किस customer को कौन-सा compensation लागू है? लिखित reply और complaint reference सुरक्षित रखें।
Transfer से पहले और समस्या के बाद Checklist
पहले amount और channel limit देखें, beneficiary name lookup करें, account number/IFSC दोबारा मिलाएं, charges पढ़ें और final confirmation screen जांचें। Transfer के बाद receipt सुरक्षित रखें और केवल sender debit को beneficiary receipt न मानें। एक receipt की copy देखकर दोबारा वही बड़ी राशि भेजना duplicate payment risk बना सकता है।
Problem होने पर bank/branch से शुरू करें, UTR-linked trace और positive confirmation मांगें, फिर bank के current grievance process का उपयोग करें। Wider complaint/escalation के लिए RBI के official current instructions पढ़ें; इस guide से automatic Ombudsman admissibility नहीं निकलती। RTGS guide कोई पैसे भेजने का form, recovery guarantee या legal determination नहीं है।
अक्सर पूछे जाने वाले प्रश्न
RTGS की minimum और maximum राशि क्या है?
RBI system में minimum ₹2 लाख है, upper ceiling नहीं। अपने bank/channel की limit और restrictions अलग जांचें।
क्या 30 मिनट Send button से गिने जाएंगे?
नहीं। Beneficiary bank के Member Interface पर payment message receipt से credit deadline है। Originating bank का message release stage अलग है।
क्या Return एक घंटे में मेरे account में पक्का आ जाएगा?
नहीं। Rule receiving member से originating member को return का है; उसके बाद original debit reverse होता है। Relevant timestamps और availability condition लागू हैं।
क्या Credit Delay का नियम स्पष्ट है?
हां। Current system regulations 11.7 beneficiary को repo rate plus 2% based compensation per day और same-day delay पर भी one-day compensation बताती है। FAQ 20 की repeated wording के बजाय यह स्पष्ट provision देखें।
क्या सभी RTGS Transfer Free हैं?
Inward free है। Outward charge ceilings और applicable tax हैं; bank lower tariff रख सकता है। Free name lookup को free transfer न समझें।
क्या UTR से RBI की Public Website पर पैसे track होंगे?
FAQ positive confirmation और bank enquiry की बात करती है, customer public tracker की नहीं। Bank को UTR देकर status trace मांगें।
Official Links और मूल स्रोत
- RBI RTGS updated FAQ
- RBI FAQ PDF, updated 14 October 2026
- RTGS System Regulations owning index
- RTGS System Regulations v 1.1 May 2026, Chapter 11
Official स्रोत जांच: 18 नवंबर 2026। आगे के संशोधन और संबंधित authority के current निर्देश लागू होंगे।
प्रस्तुति और संकलन: Ashok Nayak | Sarkari Result Digital